Skip to content

CREDI+ CLUB · A MENTORING LEAGUE SOCIETY CLUB

The only acceleration program dedicated to credit and collections.

Granting credit is easy. Scaling safely, without sinking into fraud and default, is the real challenge. Led by Marco Sousa and Jorge Azevedo, Credi+ Club turns credit, collections and cash into a decision architecture.

Limited seats per cohort.
  • 100+ companies in Latin America running the frameworks
  • 2 months expected ROI
  • 60+ AI agents specialized in credit and collections
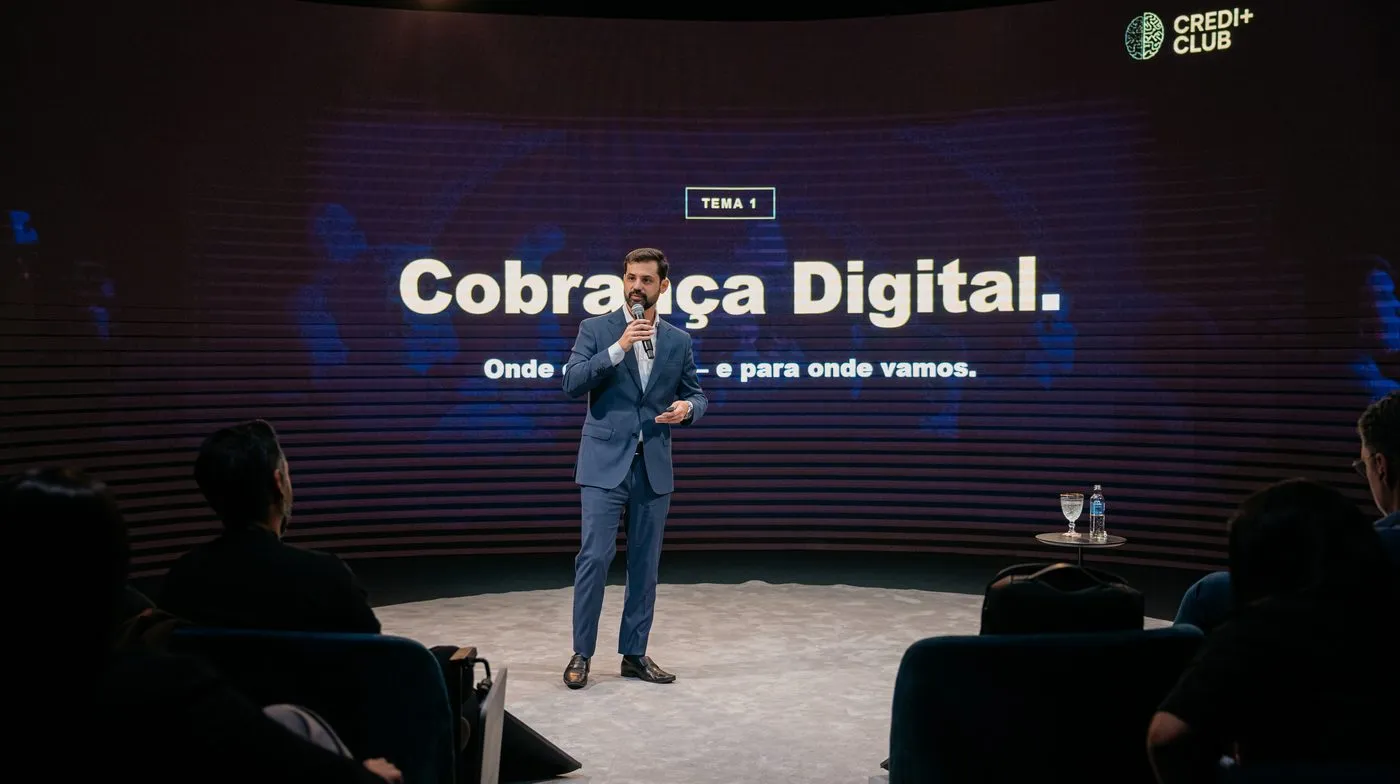
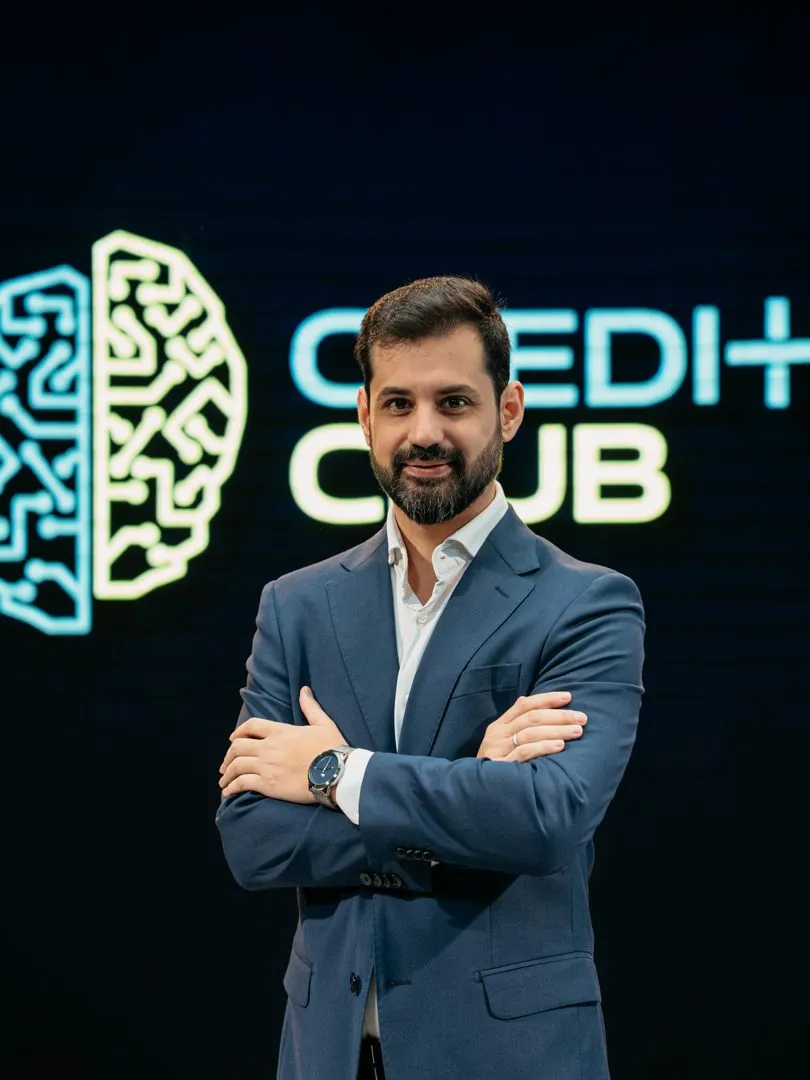
Marco Sousa in front of the Credi+ Club backdrop at the Members’ Meeting, MLS House, September 2026

THE CONTEXT

Contacting debtors has never been cheaper. Recovering has never been harder.

Defaulters have become the majority in Brazil, and the base grows every month.

  • 83.9 M Brazilians in default, an all-time record for the series
  • 51.0% of the adult population: one in every two adults
  • R$ 586 B in outstanding debt, more than four debts per person
  • 19 months of consecutive increases, with 9.3 million new defaulters

Source: Serasa, Mapa da Inadimplência e Renegociação de Dívidas, July 2026.
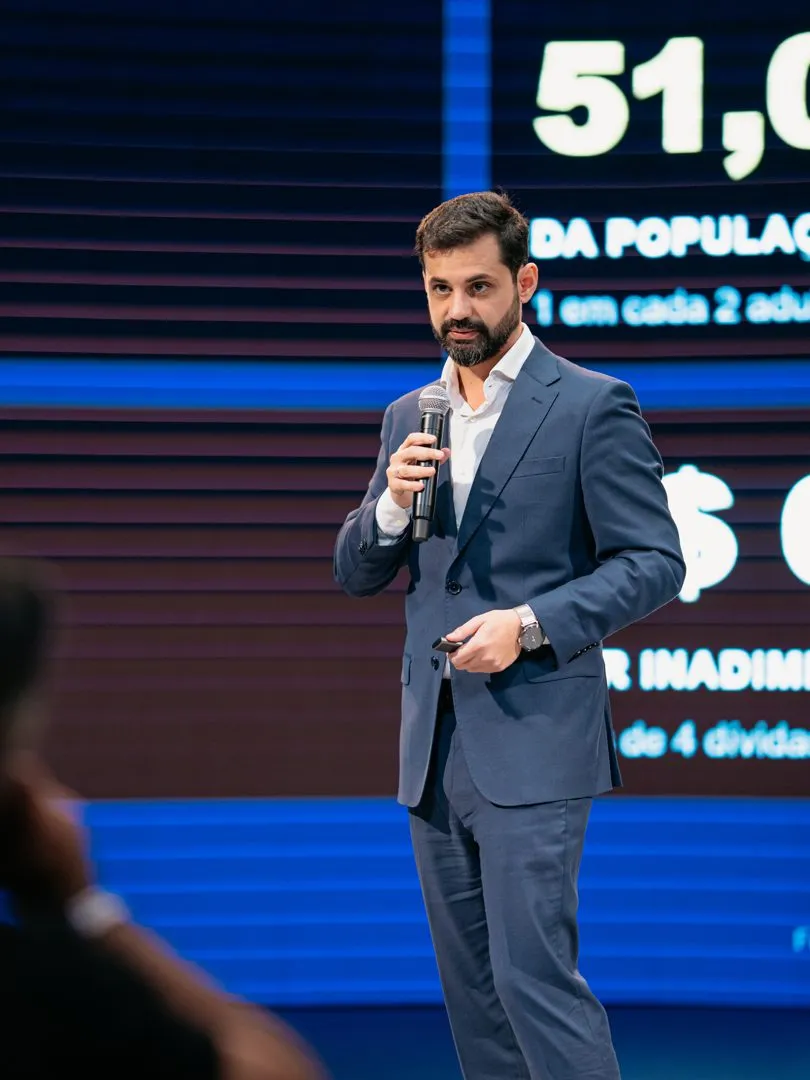
Marco Sousa on stage, in front of Brazil’s default figures
Marco Sousa at the Credi+ Club Members’ Meeting, MLS House, September 2026.

THE THESIS

What if the problem is not default, but the lack of a decision system?

Cause Consequence

Credit grows unchecked

with no real link to risk and profitability

Decisions made on gut feeling

or on generic market models

Pricing does not reflect risk

apparent margin, invisible loss

Collections arrive late

acting once the problem is already a loss

Static policies

blind to cycle, vintage and volatility

Cash becomes an afterthought

unpredictable financial results

Disconnected teams

credit, collections and finance optimize different things

No decision architecture

risk, business and accounting without integration

Loose pieces do not build a financial arm.

Credit bureaus

Deliver mountains of data and generic scores, with no intelligence for decisions tailored to the business.

Management software

Excellent for accounting and operational records, limited for predictive analysis and dynamic risk management.

Collection agencies

Focus on call volume and commission, ignoring intelligent recovery and customer lifetime value.

Fragmented result

A patchwork that creates information asymmetry, slow processes and a constant drain on ROI.

The missing piece is not another tool. It is the decision architecture that connects them all.

THE CLUB

The credit and collections club inside Brazil’s largest mentoring ecosystem.

  • Full focus 100% on credit, collections and cash flow
  • Applied knowledge frameworks validated across 100+ companies in Latin America
  • Strategic connections decision-makers, operators and vendors in the same room
  • Business environment the club generates contracts, partnerships and referrals

One club brings together those who lend, those who operate and those who supply.

Those who lend

Owners and executives of fintechs and of companies that sell on credit

  • Portfolio grows with risk under control, vintage by vintage
  • Pricing that reflects the real risk of each contract
  • Governance that supports funding and market value

Those who operate

Credit and collections executives at companies of every size

  • Recovery levers prioritized by impact
  • Capacity sized between people and AI agents
  • KPIs the board understands and sponsors

Those who supply

Owners and executives of technology and digital collections firms

  • Direct access to whoever makes the buying decision
  • Product calibrated by the real pain of operations
  • A qualified showcase inside the ecosystem

Three sides of the same table; an ecosystem that closes deals.

HOW IT WORKS

The company signs up. Its executives implement, with the mentors alongside.

  1. 01

    Operational diagnosis

    A full baseline of portfolio, collection cadence, channels, capacity and costs, led by the mentors.

  2. 02

    Implementation plan

    Levers prioritized by impact on recovery, margin and cash, with an execution sequence.

  3. 03

    Execution with the team

    Biweekly online sessions and three in-person meetings a year at MLS House; frameworks and templates applied directly to the operation by the company’s executives.

  4. 04

    Results governance

    KPIs tracked every cycle, with an executive readout ready for the board.

The club does not run the company’s collections: it develops the people who run them.

“The club does not deliver slide decks: it builds the decision architecture.”

THE DIAGNOSIS

The diagnosis shows, in numbers, where collections lose money.

The questions that unlocked the biggest opportunities in the diagnoses the mentors have already run.

01 Outreach

  • Are you calling everyone you should? At what intensity?
  • Is the intensity balanced, or is your effort going to the wrong place?
  • Is your customer contacted every day or once a week?
  • Does the extra call go to debt that can still be recovered, or to old debt?

02 Negotiation

  • Do you use every negotiation tool and objection handler, or lose negotiations at the start?
  • Do you call a lot but still fail to reach your customers?
  • At the first refusal, does your agent test another offer or give up and hang up?
  • Do you use discounts and installments as levers, or insist on the same offer for a year?

03 Bot, cadence and portal

  • Are your templates compliant, or is WhatsApp about to block you?
  • Is the live bot flow the same one you approved?
  • Does your bot offer installments and card payment, or only upfront payment?
  • Do customers who already decided to pay face passwords, re-typed data and hidden buttons on your portal?

04 Capacity

  • Is your capacity right, or have you not yet scaled your operation with AI agents?
  • Are your people busy, or is your capacity being wasted?
  • Do you call enough, or less than your customers’ other creditors?
  • Does your dialer still call invalid numbers?

05 Management and incentives

  • Are your incentives right, or is your team working against what is best for the business?
  • Do your agencies’ negotiations turn into payments, or just mark the base?
  • How much would you gain just by bringing the worst operators up to average?
  • Do broken promises wait days before being collected again?

06 Churn

  • Is your collection effort calibrated to reduce churn, or are you losing customers who could stay?
  • Do your collections talk to customers before they cancel, or after they have already left?
  • Are you losing customers because of the credit model or because of the collection process as a whole?

Without a diagnosis, every lever is a guess.

THE ORDER OF THE LEVERS

Immediate results come first.

The effort × impact matrix and cost set the order; each lever moves a number the board tracks.

  1. 01

    Low effort · immediate impact

    Free

    Dialer settings, load filters, timing, cadence and contract criteria change results with no investment.

    What it moves Cash recovered

  2. 02

    Medium effort · impact on cost

    Capacity

    Low-cost channels deliver the intensity; people handle the negotiations that close. Inefficiency is swapped for digital, not people for robots.

    What it moves Cost per real recovered

  3. 03

    Higher effort · impact on scale

    Decision

    Who to contact, when, through which channel and with which offer, decided per customer every day by AI, with human approval.

    What it moves Scale without a proportional team

WHAT THE CLUB DELIVERS

Decision, execution and control in a single ecosystem.

Models

  • Scores with Affordability Analysis, quali-quant and psychometric
  • Origination simulators (KS)

Execution

  • Intelligent digital collections
  • Risk-Based Pricing with EVA
  • Expected loss (IFRS 9)

Applied AI

  • 60+ specialized agents
  • AI orchestration: from batch to loop
  • Analysis and negotiation copilots

Control

  • Credit vintage dashboards
  • Real-time liquidity management
  • Governance and technical compliance

Analytical intelligence: from the credit simulator to Risk-Based Pricing

KS simulator and decision curves
Modeling on the real probability of default to set optimized approval cut-offs.
Risk-Based Pricing with EVA
Algorithms that ensure each contract covers its own risk and creates real economic value.
IFRS 9 framework
Expected-loss calculation to anticipate risk and protect the balance sheet.
Psychometric and quali-quant scores
Layers of analysis that capture behavior beyond bureau data.

Whoever does not price risk pays for it.

Intelligent digital collections: maximum recovery at minimum cost

Dynamic collection cadence
Channels and tone of voice automated by each customer’s profile and behavior.
Capacity simulator
Exact sizing of the operation between human and virtual agents.
Digital framework
Native channel integration: WhatsApp, email, voice and portal, in a single cadence.
Lever management
Continuous optimization of every KPI in the recovery funnel.

Collecting is a science; recovering is an automated art.

AI APPLIED TO COLLECTIONS

Collections is changing engines for the third time: decisions stop being manual.

  1. 1.0 · Human scale

    Every contact cost headcount

    Dialer, seats and script. Recovering more meant hiring more.

  2. 2.0 · Digital scale

    The cost of contact collapsed

    SMS, WhatsApp, portal and voice agents. Deciding who, when and how stayed human and in batches.

  3. 3.0 · Decision scale

    AI decides per customer

    Channel, timing, tone and offer set customer by customer, within a budget, every cycle.

From batch to loop: five roles, and sensitive calls stay with people.

  1. LLM Monitor Reads the portfolio every day and derives targets per segment.
  2. LLM + Modeling Orchestrator Tailors the plan per customer, within the budget.
  3. Human Approval The day’s plan in one click; sensitive cases one by one; a kill switch only a human can turn back on.
  4. Deterministic Executor Sends exactly what was approved through the channels.
  5. Isolated LLM Auditor Reconciles 100% of what went out and feeds the next cycle.

Already running on a real portfolio: the LLM thinks, code executes, a human approves what is sensitive and can switch everything off. It starts with early prevention, then early delinquency and escalation.

Digital solved the cost of contact; it did not solve the decision.

THE ASSET LIBRARY

60+ AI agents working in the operation.

Brazil’s largest library of agents specialized in credit and collections.

Diagnostic agents

Map operational bottlenecks and point to the highest-impact opportunities.

Negotiation agents

Automate proposals and handle complex agreements within the authorized cadence.

Risk and legal assistants

Support critical credit and legal-compliance decisions.

Productivity copilots

From technical manuals to balance-sheet analysis in seconds.

AI does not replace the manager; it gives the manager superpowers.

What the club has already built with its members Non-exhaustive list.

Thematic sessions held

  • Digital collections and the risk of WhatsApp bans
  • Prototype of a WhatsApp collections agent
  • Assessment of credit projects
  • Capacity: operational diagnosis and planning
  • Risk models, bias and AI
  • Collections funnel and installed-capacity levers
  • Champion call and voice bot: a practical case
  • Operational commissions and compensation
  • Collections efficiency with real portfolio data

Library and playbooks

Choque de Gestão Financeira
Behind the scenes of liquidity management in SMEs
Guia de Capacidade Ideal
Technical sizing of high-performance operations
Inimigos da Liquidez
The bottlenecks that destroy company cash
Risk Based Pricing
The reference on risk-based pricing in the Brazilian market
Playbooks and templates
Cadences by bucket and channel, portfolio segmentation, negotiation scripts, metrics by attempt, channel and operator, governance

Diagnostic engine

Scripts that read the dialer base, the invoice portfolio, call recordings, the bot script and the payment portal, and return auditable findings within hours:

  • Intensity, penetration and voicemail per customer
  • Contact, promise and payment funnel
  • Dispersion across operators and agencies
  • Human capacity × digital agent
  • Quality of calls and bot conversations
  • Portal steps through to payment

Information is abundant; structured knowledge is rare.

THE RESULT

From chaos to financial freedom: a structured financial arm, for every size.

Immediate liquidity

Cash released by intelligent asset recovery and a shorter financial cycle.

Protected margins

A sharp drop in LGD through risk-based pricing and precise decision models.

Scalability

Sales grow fast without a proportional surge in default.

Market value

Governance and processes that make the company attractive to investors and financial institutions.

The end goal is not credit; it is financial freedom and scale.

THE CLUB, LIVE

Members’ Meeting at MLS House.

September 1, 2026 · a full day of content, panels and networking, from 9am to 8pm.
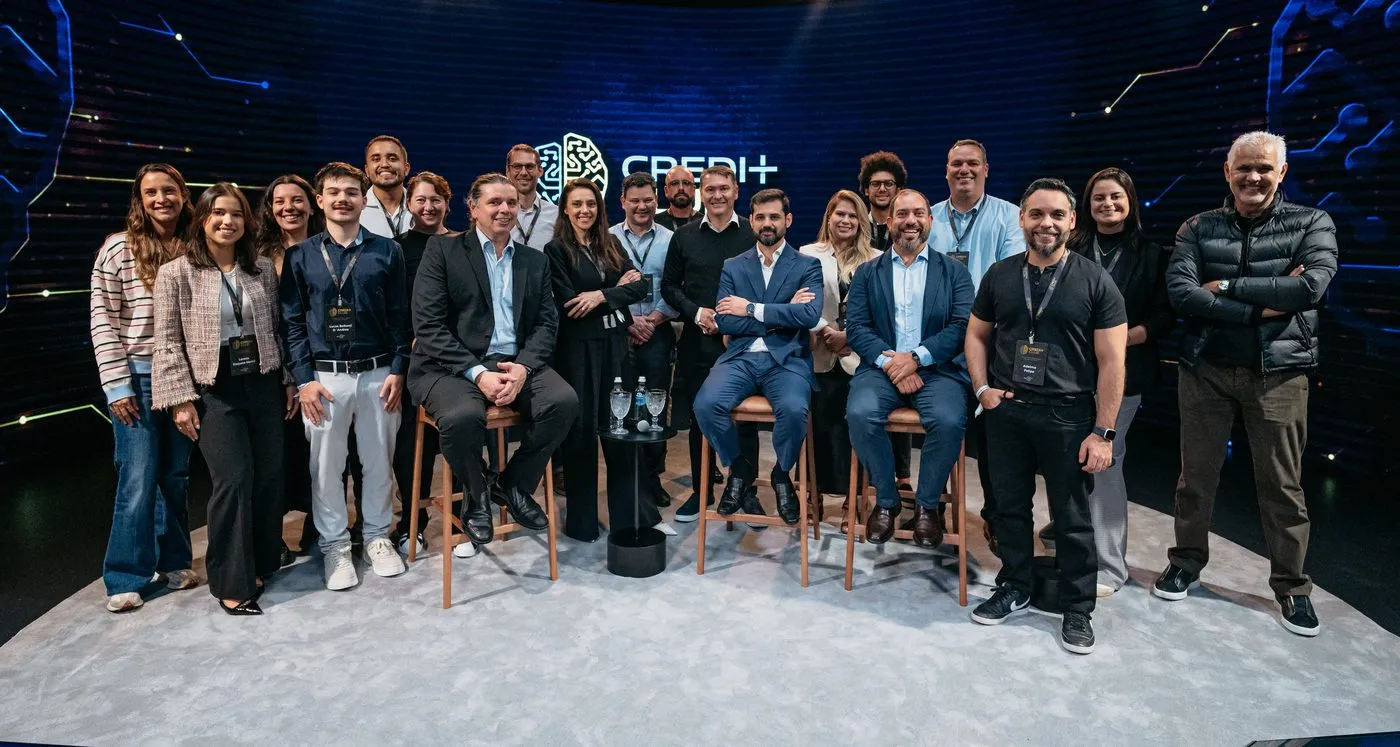
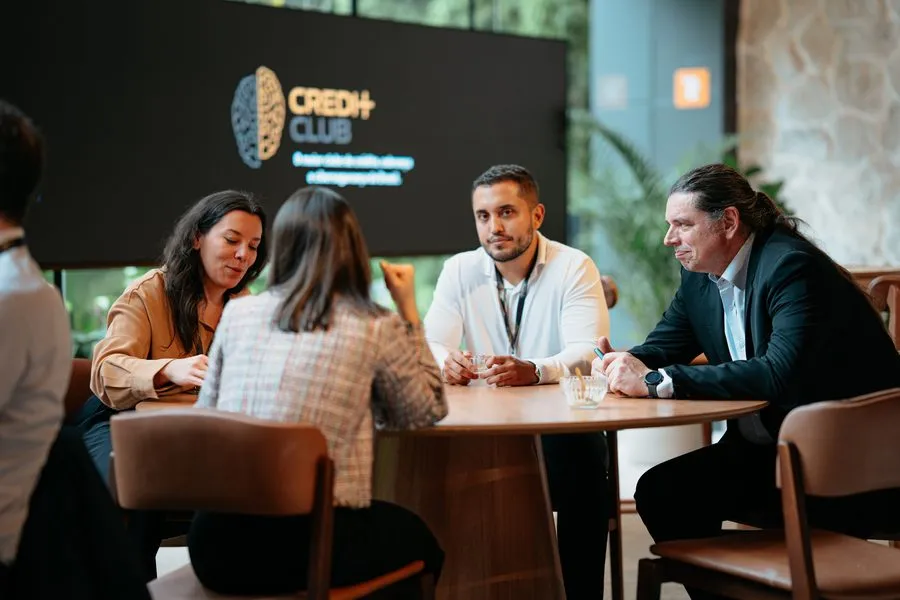
The Members’ Meeting cohort, MLS House, September 2026
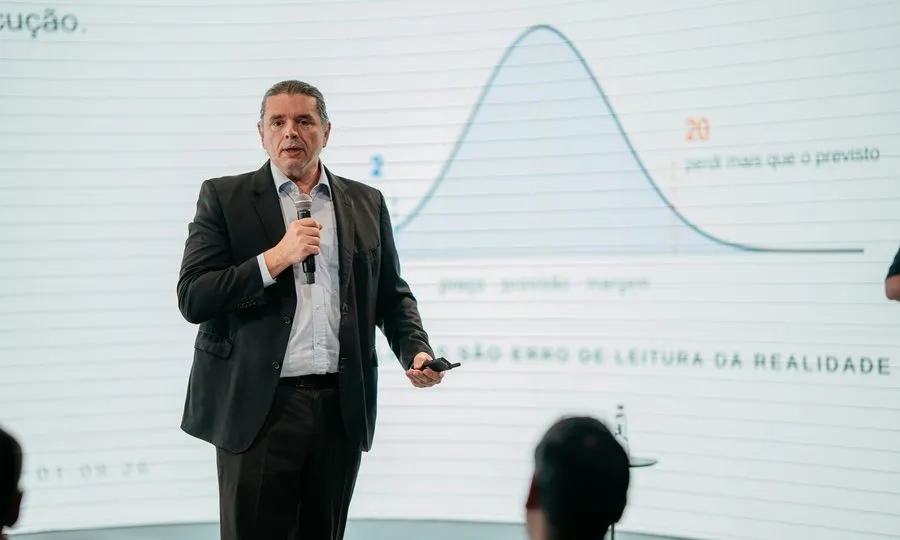
Digital collections and AI orchestration, with Marco Sousa
Credit after the disruption, with Jorge Azevedo
Guided networking between sessions
Closing cocktail: the club generates contracts, partnerships and referrals

Who sits at the table: credit, collections and technology executives, side by side with the mentors and with the decision-makers.
  • Biweekly online sessions
  • 3 in-person meetings a year at MLS House
  • Platform with recordings and frameworks
  • Podcast and business network
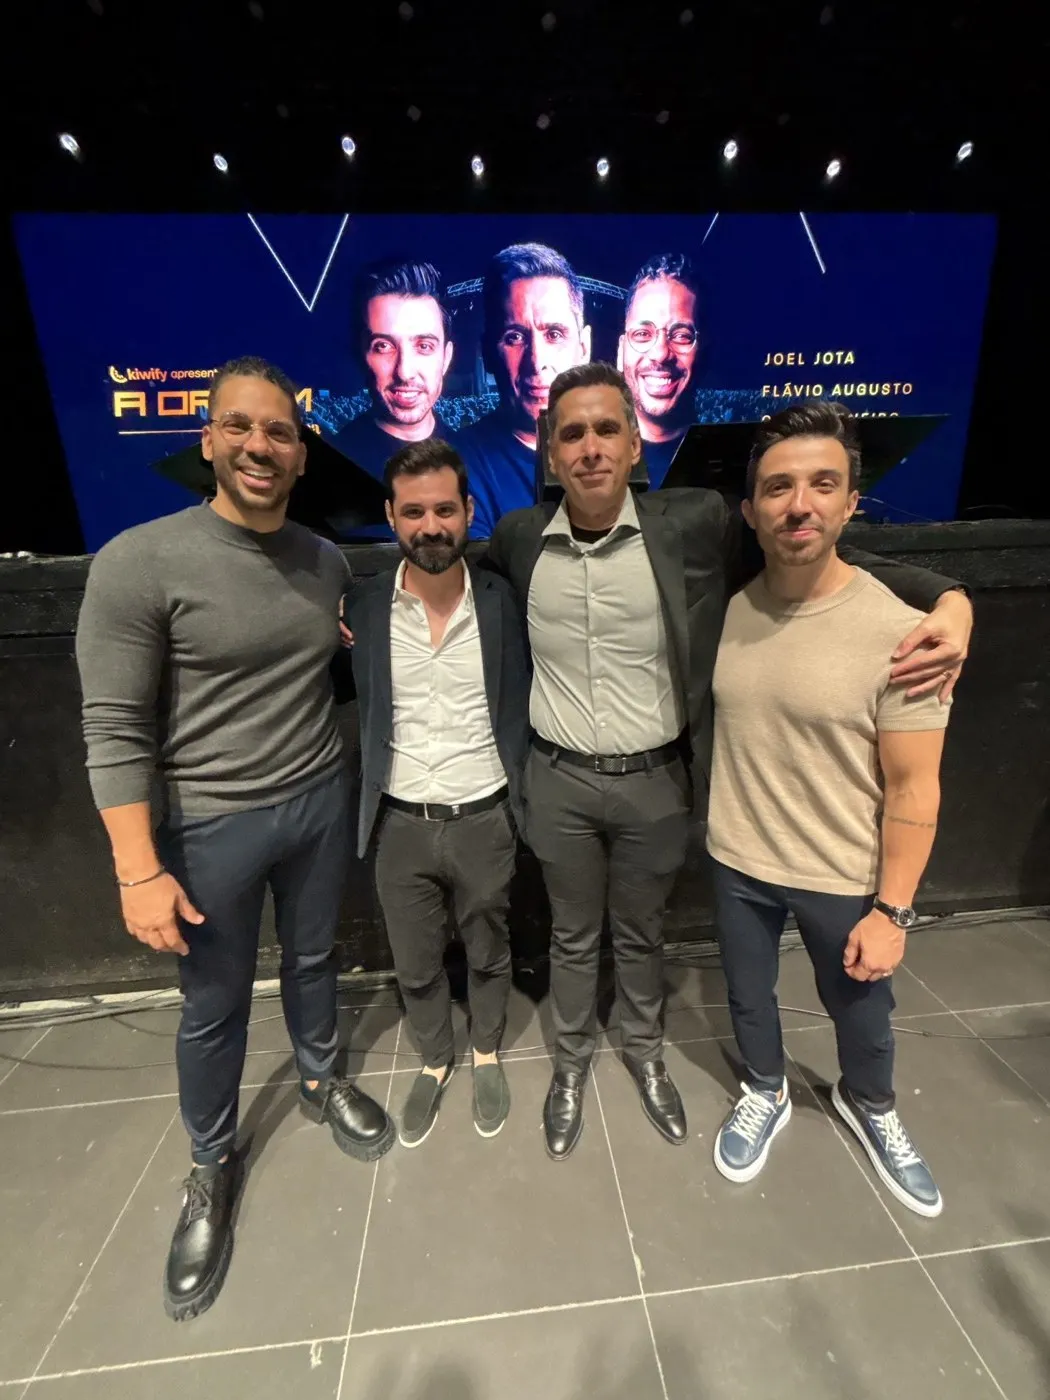
Marco Sousa on stage with the founders of the Mentoring League Society
Marco Sousa with the founders of the Mentoring League Society.

MENTORING LEAGUE SOCIETY

Inside Brazil’s largest mentoring ecosystem.

Credi+ Club is the credit and collections club of the Mentoring League Society, the league of mentors founded by Flávio Augusto, Joel Jota and Caio Carneiro.

League endorsement
the official club on the topic within the MLS ecosystem
MLS network
a business environment alongside the ecosystem’s major players
Club membership
limited seats, as in the great clubs
League standard
audited method, governance and mentoring rules

THE MENTORS

Who leads the transformation.

Marco and Jorge take part in every session. No junior mentor in between: executive-level decisions, from the people who built the operations that became the benchmark.
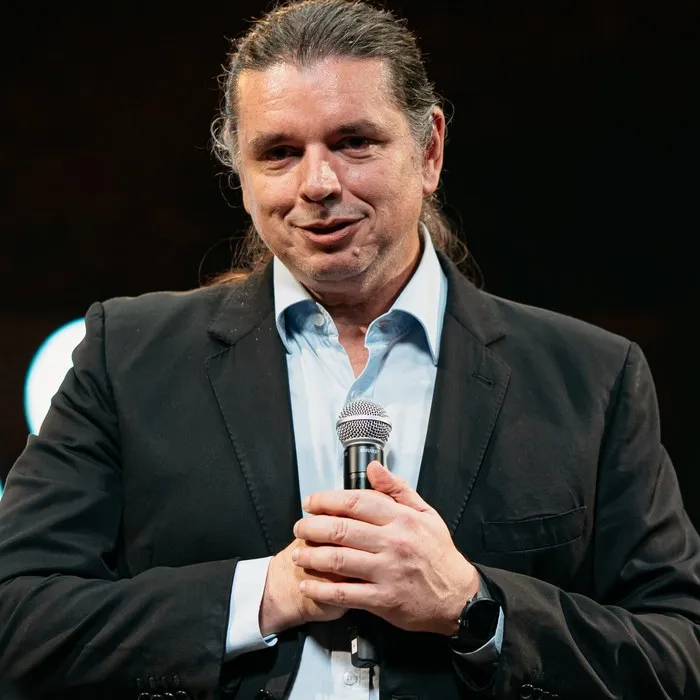
Jorge Azevedo

Jorge Azevedo

Co-founder · Credi+ Club

  • One of Latin America’s leading credit and collections specialists.
  • 25 years of experience, including McKinsey, EY, Accenture and AT Kearney.
  • More than 180 transformations at major financial institutions and fintechs.
Marco Sousa

Marco Sousa

Co-founder · Credi+ Club · VP of Operations, Principia

  • Board member, co-founder and VP of Operations at Principia, an education-credit fintech serving more than 760,000 students.
  • Nearly two decades in international credit and collections: McKinsey, Azul, TIM Brasil and Mutant.
  • Built one of Brazil’s pioneering digital collections operations.

“Whoever masters credit and collections today leads the financial future of companies.”

HOW TO START

Start with a diagnosis of the operation.

  1. 01

    Initial operational diagnosis

    The credit, collections and cash baseline that reveals where money is stuck, where inefficiency is eating into results and where it drives churn.

  2. 02

    Plan and seats at Credi+ Club

    Implementations prioritized by impact, executed by the company’s executives with the mentors alongside.

  3. 03

    Immediate access to the asset library

    Frameworks, playbooks, templates and the 60+ AI agents from day one.

This system is not available on the market.

It already exists. It already works. It already delivers results. Until now, only large operations had access to it.

From project to continuous system. From recommendation to automated decision. From analysis to direct EBITDA impact.

It is not about learning. It is about operating with infrastructure, in a select group of companies.

FREQUENTLY ASKED

What people usually ask.

Who is Credi+ Club for?

For companies that grant credit or sell on installments, for credit and collections executives at operations of every size, and for technology and digital collections companies. The company signs up; its executives take part.

Is it a course, a consultancy or software?

None of the three on its own. It is a club with a format close to consulting: an operational diagnosis, a prioritized implementation plan and execution supported by the mentors. The club does not run the company’s collections: it develops the people who run them.

How does the diagnosis work?

The mentors build the baseline of portfolio, cadence, channels, capacity and costs, and show in numbers where collections lose money. The diagnosis sets the order of the levers: first the ones that cost nothing, then capacity, then automated decisions.

How long until there is a return?

The club works with an expected ROI within 2 months. The first levers, such as dialer settings, timing, cadence and contract criteria, change results with no investment.

What is the meeting format?

Biweekly online sessions, three in-person meetings a year at MLS House and a platform with recordings, frameworks and templates. Members also have the club’s podcast and business network.

What are the 60+ AI agents?

A library of agents specialized in credit and collections: diagnostic agents, negotiators, risk and legal assistants and productivity copilots. Members have access from day one.

The operation is small. Does it still make sense?

Yes. The method starts from a diagnosis of each operation’s reality and has been applied at companies of every size, from SMEs to operations with millions of customers.

What is the relationship with the Mentoring League Society?

Credi+ Club is the official credit and collections club of the Mentoring League Society, the league of mentors founded by Flávio Augusto, Joel Jota and Caio Carneiro. Members take part in the MLS ecosystem’s business environment.

How to start?

With the initial diagnosis of the operation. Just fill in the form below; the reply comes by email to schedule the conversation.

START WITH THE DIAGNOSIS

Request a diagnosis of the operation.

For companies that want to know, in numbers, where collections lose money. Requests are reviewed individually by the mentors, and the reply comes by email.

By submitting, you agree to be contacted by the Credi+ Club team. Your data privacy is respected.